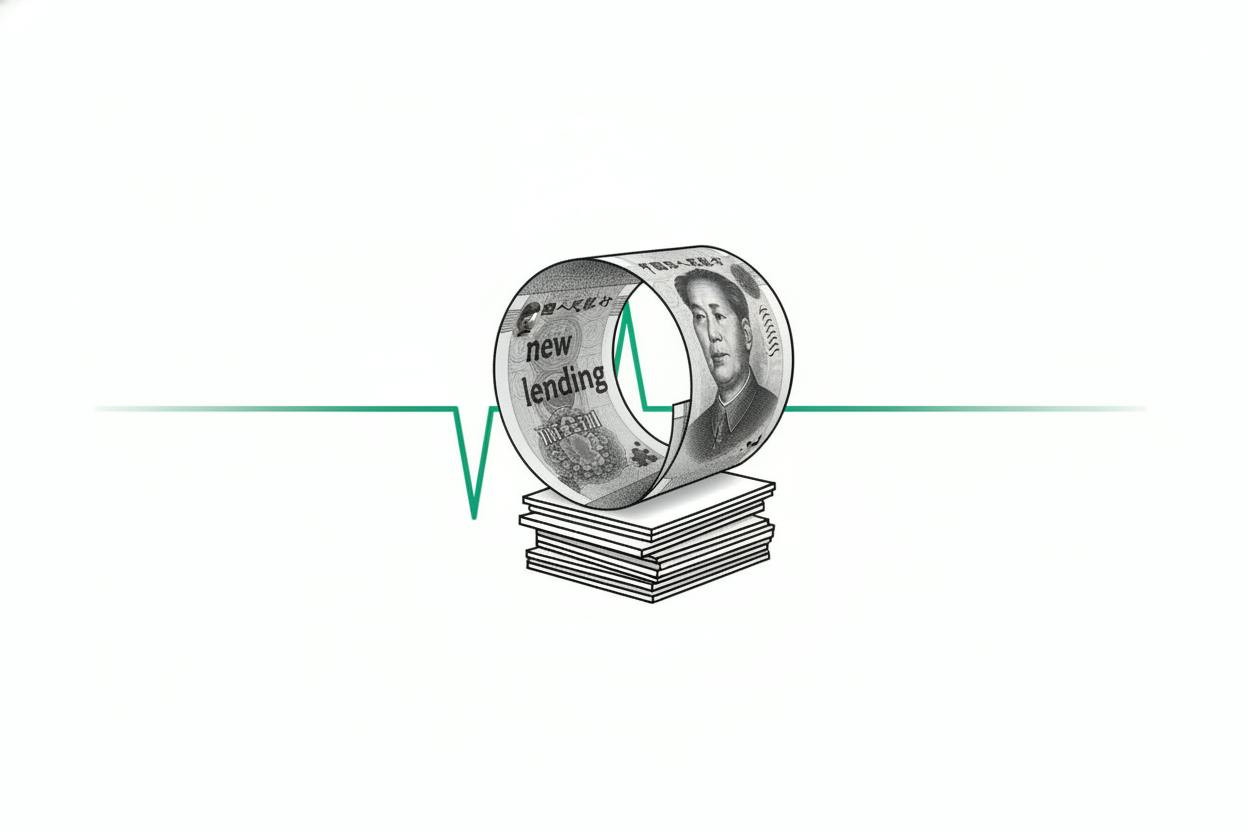
China's banks extended far less credit than expected in October, a fresh sign that households and businesses remain reluctant to borrow even after policymakers rolled out support measures in late September. New yuan loans fell by 100 billion yuan compared with the previous month, according to Reuters, underscoring the persistent weakness in credit demand.
The drop in lending is a closely watched indicator for the world's second-largest economy. When banks lend more, it typically signals that companies are investing and consumers are spending. When lending slows, it suggests caution—and that can weigh on economic growth.
Why credit demand is still weak
The October figure comes on the heels of a package of stimulus measures announced in late September, which included interest rate cuts and steps to support the property market. Those measures were designed to encourage borrowing and spending, but the latest data suggests they have yet to translate into a meaningful pickup in credit appetite.
Several factors are likely at play. The property sector, a major driver of loan demand in China, remains under pressure. Homebuyers are hesitant to take on mortgages, and developers are focused on reducing debt rather than expanding. Meanwhile, businesses—especially smaller firms—may be holding back on investment as they wait for clearer signs of a sustained recovery.
Household borrowing, which includes mortgages and consumer loans, has also been sluggish. Consumer confidence has been slow to recover, and many families are choosing to save rather than spend, a trend that has persisted for much of the past year.
What this means for investors
For investors, weak lending data is a signal that China's economic recovery is still uneven. It can affect everything from corporate earnings to commodity prices, and it often influences global markets because China is a major buyer of raw materials and a key link in global supply chains.
If credit demand remains soft, it could put pressure on Chinese banks' profit margins, since lending is their core business. It could also mean slower growth for companies that depend on domestic consumption or construction. On the other hand, the data may increase the likelihood of further stimulus from Beijing, which could provide a boost to markets down the line.
Investors should watch for additional policy moves, such as further rate cuts or targeted support for specific sectors. They should also keep an eye on upcoming economic data, including retail sales and industrial production, to gauge whether the weakness in lending is spreading to the broader economy.
The October lending figures are a reminder that policy support doesn't always translate into immediate results. For everyday investors, it's a useful gauge of how quickly China's economy is regaining momentum—and whether the global growth outlook is improving or deteriorating.
In related news, China's copper smelters are bracing for a rare pricing squeeze, which could signal broader industrial weakness. And while some Asian markets have shown resilience, India's Nifty 50 slipped as inflation there topped the central bank's target, highlighting the mixed picture across the region.
For now, the takeaway is that China's credit engine is still sputtering. Whether that changes will depend on how quickly the latest stimulus filters through to the real economy—and whether households and businesses start feeling confident enough to borrow again.