Crocs is set to report its third-quarter results soon, and investors are closely watching North America. But UBS Securities, an investment bank, says a quiet accounting change involving Amazon could make the numbers look worse than the underlying demand really is.
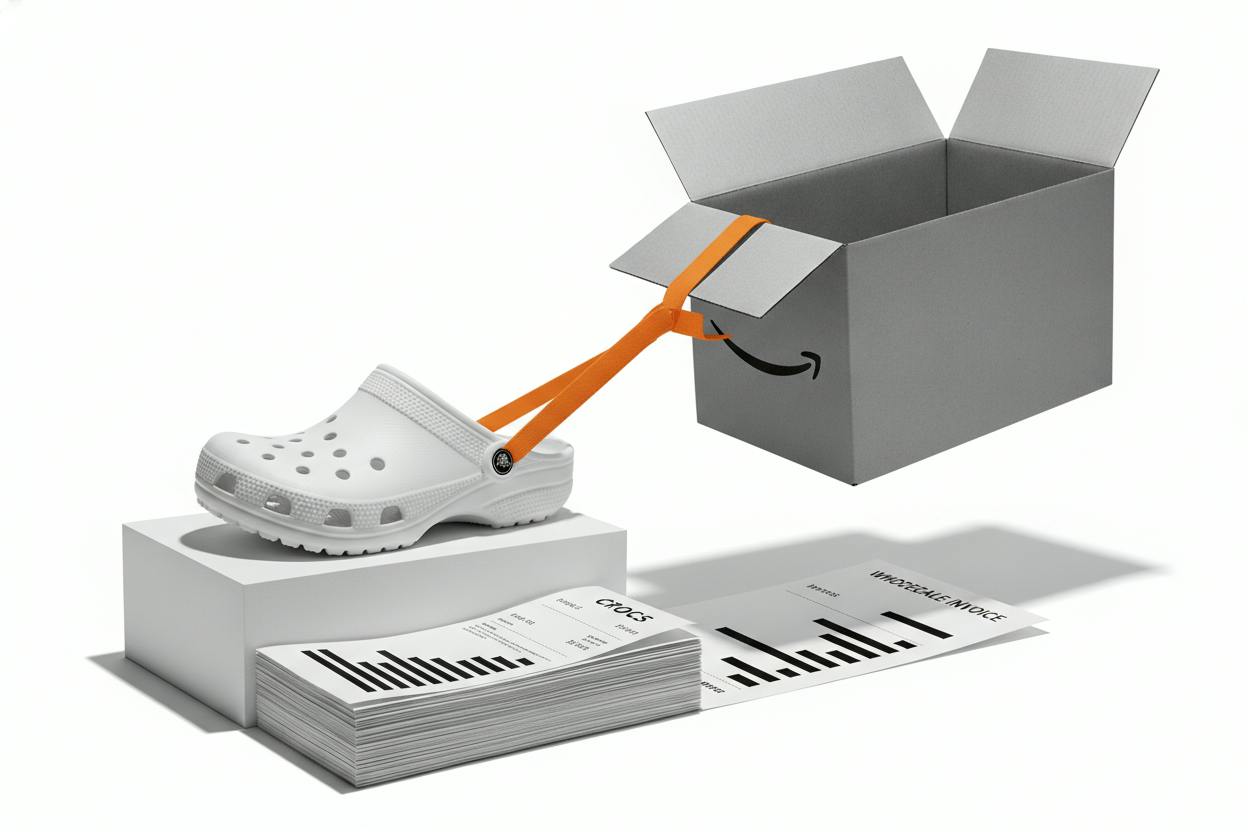
According to UBS, Crocs shifted its Amazon business at the start of Q3 from a third-party arrangement to a first-party one. In the old setup, Crocs sold directly to shoppers on Amazon's marketplace. Now, Crocs sells its inventory to Amazon, which then sells it to customers. This change means those sales are now recorded as wholesale rather than direct-to-consumer (DTC).
Wholesale revenue is typically lower than DTC revenue because the retailer—in this case, Amazon—takes a cut and sets the final price. So even if the number of shoes sold stays the same, the reported revenue from those sales will be smaller. UBS suggests this could weigh on Crocs' North America revenue in Q3, even if international demand remains solid.
Why the accounting shift matters
For everyday investors, the key takeaway is that a drop in reported revenue doesn't necessarily mean fewer people are buying Crocs. It could simply be a reflection of how the company recognizes sales. This is a common distinction in retail: DTC sales are recorded at full retail price, while wholesale sales are recorded at the price the manufacturer charges the retailer, which is lower.
Crocs has been growing its DTC channel in recent years, partly because it offers higher margins and more control over branding. Moving Amazon to a wholesale model might seem like a step backward, but it could also simplify operations and reduce shipping and customer service costs. Amazon is a massive sales channel, and having it as a wholesale partner could provide more predictable volume.
The shift also highlights a broader trend: companies are increasingly relying on marketplaces like Amazon, even if it means sacrificing some revenue recognition. For Crocs, the move could be a strategic decision to streamline its supply chain or to align with Amazon's preferences for certain product categories.
What to watch in the Q3 report
When Crocs reports, investors should look beyond the headline revenue number. UBS's note suggests that North America revenue might miss expectations, but that could be due to the accounting change rather than a slowdown in consumer demand. International sales, which have been a growth driver for Crocs, could help offset some of the drag.
Investors should also pay attention to any commentary from management about the Amazon transition. If the company explains the shift clearly, it could reassure the market that the underlying business is healthy. On the other hand, if the company is vague, investors might worry that the change is masking deeper issues.
Crocs has been a popular brand, especially among younger consumers, and its clogs have become a cultural staple. The company has also expanded into sandals, sneakers, and other footwear categories. But like many retailers, it faces challenges from inflation, supply chain costs, and shifting consumer preferences.
In the broader market, investors are already dealing with a mix of earnings reports and economic data. For instance, Wall Street edged higher recently on the back of a major tech acquisition, showing that sentiment can shift quickly. Crocs' report will add to the picture of consumer spending, which is a key driver of the economy.
What it means for investors
For those holding Crocs stock, the key is to distinguish between accounting noise and real business performance. If the company beats on earnings per share but misses on revenue due to the Amazon shift, that could be a positive signal. Conversely, if both miss, it might indicate a genuine slowdown.
It's also worth noting that Crocs has a history of strong brand loyalty and has managed to maintain pricing power. The company's direct-to-consumer business has been a bright spot, and the Amazon change could free up resources to focus on that channel.
Investors should also consider the broader retail environment. Consumer spending has been resilient, but there are signs of caution, especially among lower-income households. Retailers like Steel Dynamics have shown that even strong sales can be overshadowed by profit misses. Crocs will need to navigate these headwinds while explaining the Amazon impact.
Ultimately, the UBS note is a reminder that not all revenue declines are created equal. For Crocs, the shift to wholesale with Amazon could be a one-time adjustment that makes Q3 look weaker than it really is. Long-term investors should focus on the company's ability to grow its brand and expand internationally, rather than getting caught up in quarterly accounting quirks.
As the earnings date approaches, expect more analysis from Wall Street. Some analysts may adjust their estimates to account for the Amazon change, which could lead to volatility in the stock. But for those who understand the underlying dynamics, the Q3 report could offer a buying opportunity if the market overreacts to the headline numbers.