NVRO Metals, a miner listed on the TSX Venture Exchange, is looking to raise up to CA$35 million through a private placement. The company is selling units at CA$0.13 each, with each unit consisting of one common share and a three-year warrant. The proceeds are earmarked to fund its acquisition of Northern Territories Resources.
The announcement sent NVRO's shares down 16% to CA$0.13 on the TSX Venture Exchange, reflecting the dilutive nature of the offering and the discount to recent trading levels.
Details of the offering
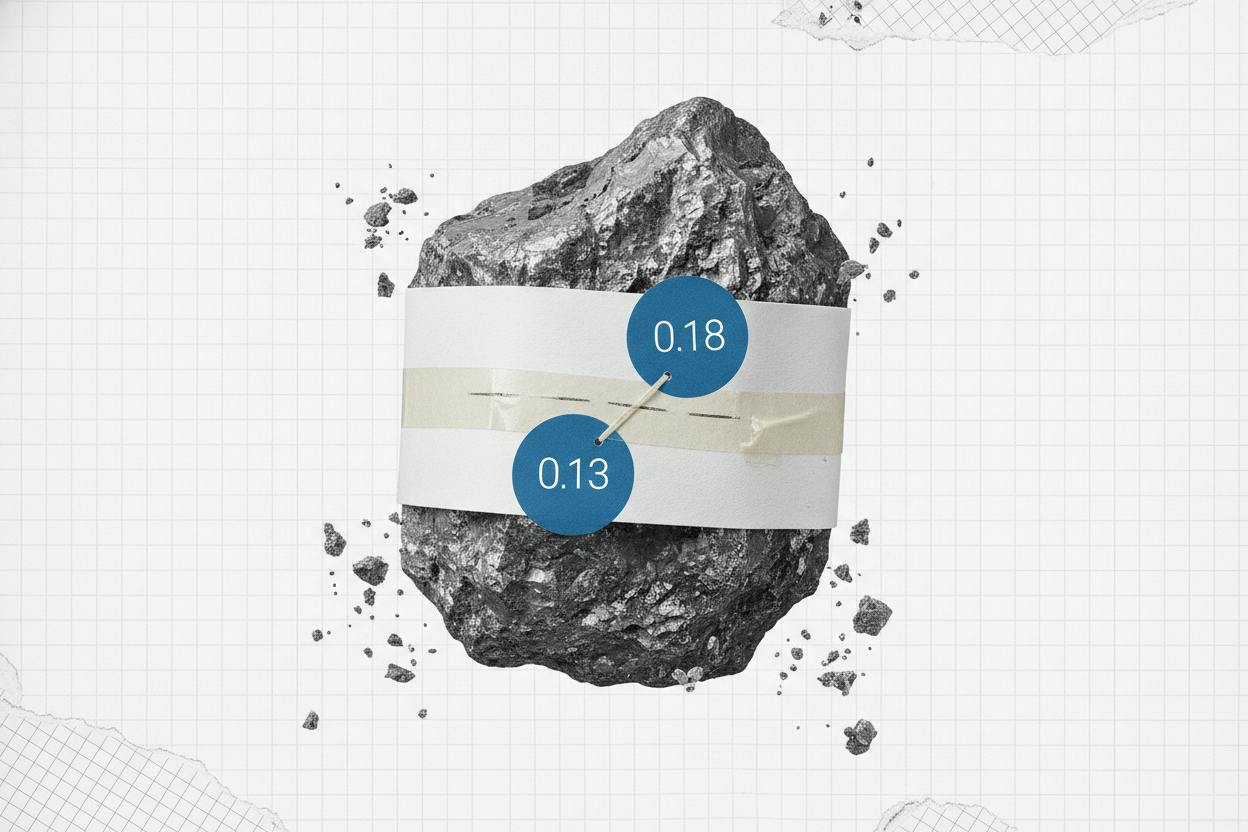
NVRO says it is conducting a best-efforts private placement of 269.2 million units at CA$0.13 per unit. The company also has a 15% over-allotment option, which could increase the total raise if investor demand is strong.
Each unit includes one common share plus a warrant that allows the holder to buy an additional share at a fixed price of CA$0.18 for three years. Warrants are a common sweetener in such deals—they give investors the right, but not the obligation, to buy more shares later at a set price. This can make the offering more attractive, but it also means potential future dilution if the stock rises above the warrant price.
Private placements like this are a typical way for junior miners to raise capital, especially when they need funds for acquisitions or exploration. The use of units with warrants is a standard structure, allowing companies to offer a slightly lower price while giving investors a potential upside.
What it means for investors
For current shareholders, the immediate impact is dilution. The issuance of 269.2 million new shares—potentially more with the over-allotment—will increase the total share count, reducing the ownership stake of existing investors. The 16% drop in the share price reflects this concern, as well as the fact that the offering price is at the current market price, which is often seen as a signal that the company needs cash quickly.
The warrants add another layer of potential dilution. If NVRO's stock climbs above CA$0.18 within three years, warrant holders could exercise their rights, bringing in additional cash to the company but also issuing more shares. This is a common trade-off for growth-focused miners.
On the positive side, the funds will help NVRO complete its acquisition of Northern Territories Resources. If that deal adds valuable assets or production, it could boost the company's long-term prospects. Investors will want to watch how the acquisition is integrated and whether it delivers on its promises.
Similar capital raises have been seen across the sector. For example, Entree Resources raised CA$31.9 million through a private placement with warrants, and Western Investment raised CA$50 million to fund acquisitions. These deals are a lifeline for companies needing capital, but they always come with dilution.
Looking ahead
Investors will be watching a few key things in the coming weeks. First, whether the placement is fully subscribed, including the over-allotment option. Second, the terms of the Northern Territories Resources acquisition and what it brings to NVRO. Third, how the company plans to use the funds beyond the acquisition—whether for exploration, development, or working capital.
For everyday investors, this story highlights the risks and rewards of investing in junior miners. Capital raises can provide the fuel for growth, but they also dilute existing shareholders. It's important to weigh the potential benefits of the acquisition against the cost of dilution.
As always, do your own research and consider your risk tolerance. The TSX Venture Exchange is known for its high-risk, high-reward listings, and NVRO is no exception.