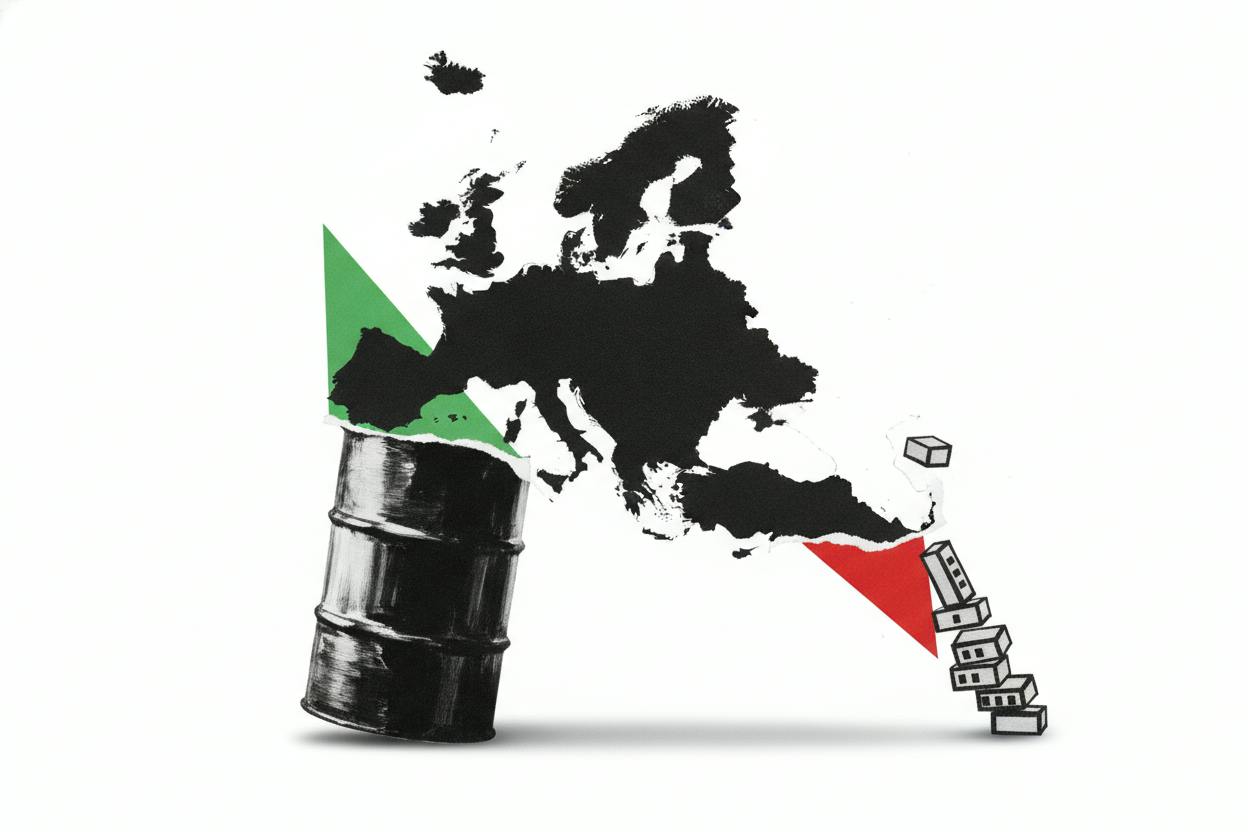
Europe's largest listed companies are heading into the third-quarter earnings season with a strong headline forecast. Analysts expect profits for the STOXX Europe 600 — a broad index of major European stocks — to climb 19.4% compared with the same period last year. The surge is led by the energy sector, where earnings are projected to jump a staggering 98.6%.
At the other end of the spectrum, real estate companies are bracing for a sharp downturn, with earnings expected to slide 71.4%. That stark contrast highlights the uneven recovery across Europe's corporate landscape.
Why energy is booming
The energy sector's explosive growth is largely a reflection of higher oil and gas prices over the past year. When energy prices rise, producers and related companies see their revenues and profits expand dramatically. For investors, this means energy stocks could be a bright spot in the upcoming earnings reports, potentially boosting share prices and dividends.
However, the same energy costs that benefit producers are a burden for other industries. High energy prices squeeze margins for manufacturers, airlines, and chemical companies, and they also feed into inflation, which can influence central bank policy. As European stocks have slipped recently amid rising bond yields, the earnings season will be a key test of whether high valuations are justified.
Real estate's steep decline
The real estate sector's projected 71.4% earnings drop is a stark reminder of the challenges facing property companies. Higher interest rates have made borrowing more expensive, which increases financing costs for real estate firms and reduces demand for properties. Additionally, falling property values can lead to write-downs, further hurting profits.
For investors, this means real estate stocks may continue to underperform. The sector is sensitive to interest rate movements, and with rising US yields pressuring global markets, the outlook remains cautious. Some real estate investment trusts (REITs) might offer attractive yields, but the earnings decline suggests underlying weakness.
What this means for investors
The overall 19.4% earnings growth forecast is encouraging, but it masks significant divergence. Investors should look beyond the headline number and consider sector-specific trends. Energy stocks may offer growth, but they are also cyclical and can be volatile. Real estate, on the other hand, faces headwinds from high rates, but that could also mean some stocks are undervalued if the sector stabilizes.
It's also worth noting that earnings forecasts are just estimates. Actual results can differ, and companies often provide guidance that moves markets. As the earnings season unfolds, watch for surprises in both directions.
The broader context includes US earnings expectations, which are also strong, but with wild cards like AI spending and interest rates. In Europe, energy costs and political factors have weighed on the euro, as seen in the euro's recent drop below $1.13. A weaker euro can actually help European exporters by making their goods cheaper abroad, which could support earnings in other sectors.
How to approach the numbers
For everyday investors, the key takeaway is to diversify. Relying too heavily on one sector, whether it's energy or real estate, can be risky. The earnings season is a good time to review your portfolio and ensure it aligns with your risk tolerance and long-term goals.
Remember, past performance is not a guarantee of future results. While the energy sector's growth is impressive, it may not be sustainable if oil prices fall. Similarly, real estate could rebound if interest rates ease. Keep an eye on company-specific news and broader economic indicators.
As always, this is not financial advice. It's important to do your own research or consult a professional before making investment decisions.