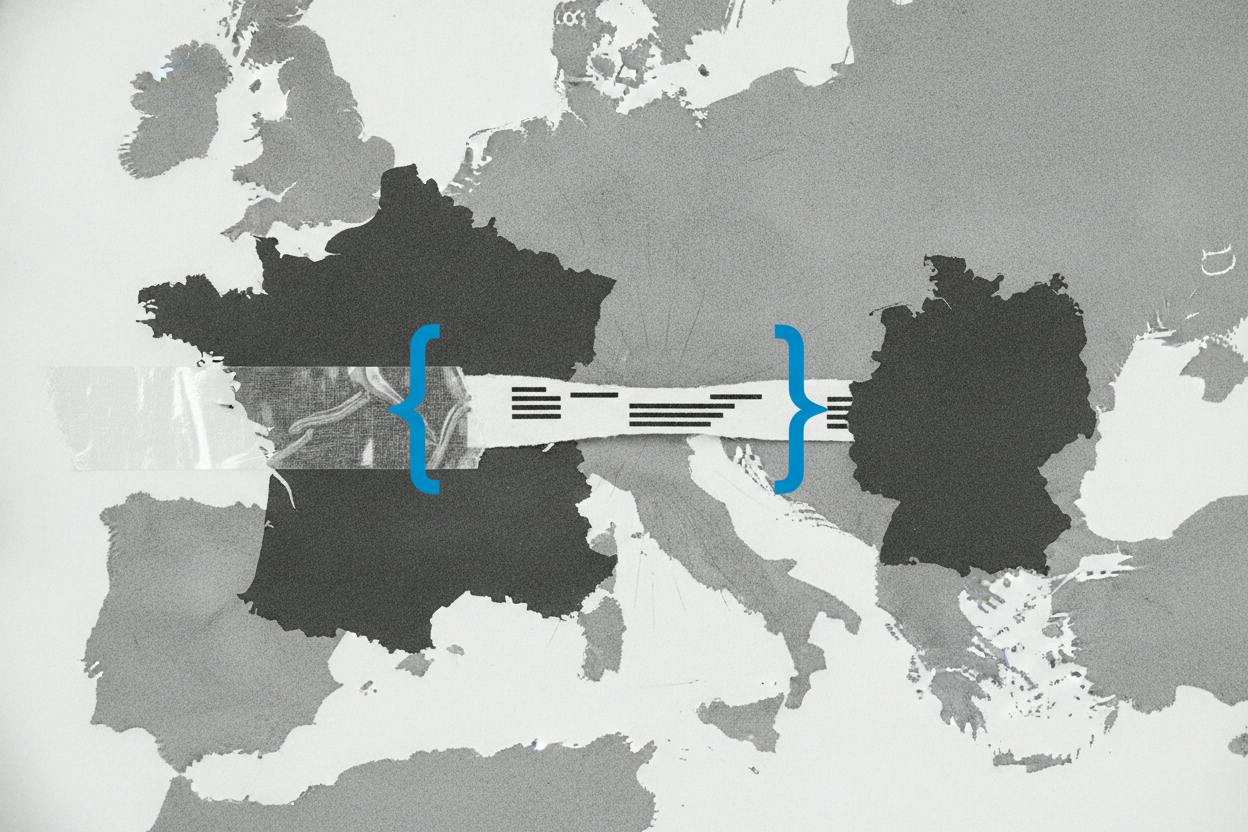
France's borrowing costs are climbing faster than Germany's, a sign that investors are demanding a bigger premium to lend to Paris. The yield on France's 10-year government bond reached 4.78%, and the gap over Germany's equivalent bund widened to 120 basis points—the largest since 2012.
That gap, known as the OAT–Bund spread (OAT stands for Obligations Assimilables du Trésor, France's benchmark bond), is a simple measure of how much extra return investors require to hold French debt instead of German debt. A wider spread means investors see more risk in lending to France relative to Europe's largest economy.
Why the spread is widening
The main driver is inflation. Price pressures across Europe have remained stubbornly high, keeping central banks cautious about cutting interest rates. That has pushed up yields on government bonds across the region, but France is feeling the pinch more than Germany.
Part of the reason is supply. France is heading into a heavy refinancing period, with the government planning a record €340 billion of bond sales next year. That means a lot of new debt hitting the market, which can weigh on prices and push yields higher. Investors often demand a higher return when they see a large wave of supply coming.
Germany, by contrast, is seen as a safe haven. Its economy is larger and its fiscal position is generally viewed as more solid, so investors tend to flock to German bunds during times of uncertainty. That dynamic has been pushing the two countries' borrowing costs in opposite directions.
What this means for investors
For everyday investors, the widening spread is a reminder that not all government bonds are created equal. While both France and Germany are considered low-risk compared with corporate bonds, the extra yield on French debt reflects a slightly higher level of perceived risk.
If you hold bond funds or ETFs that include European government debt, you may see some volatility as these spreads move. But for most investors, the day-to-day changes in the OAT–Bund spread are unlikely to have a direct impact on their portfolios unless they are heavily invested in European fixed income.
The broader picture is that bond yields across developed markets have been climbing. In the US, the 10-year Treasury yield has been hovering near multi-year highs, and similar trends are playing out in Europe. This is part of a global repricing of interest rate expectations, as investors adjust to the possibility that central banks will keep rates higher for longer.
For those with savings accounts or certificates of deposit, higher bond yields can be a positive, as banks often pass on some of the increase to savers. But for borrowers, especially those with variable-rate loans, the trend is less welcome.
What to watch next
Investors will be watching inflation data closely. If price pressures ease, central banks may feel more comfortable cutting rates, which could help narrow the spread. On the other hand, if inflation stays hot, yields could keep climbing and the spread could widen further.
France's refinancing plans will also be in focus. The record €340 billion of bond sales next year will test investor appetite for French debt. If demand is strong, the spread might stabilize; if not, it could widen even more.
For now, the message is clear: France's borrowing costs are moving away from Germany's, and that trend is worth monitoring for anyone with exposure to European bonds or an interest in how governments fund their spending.