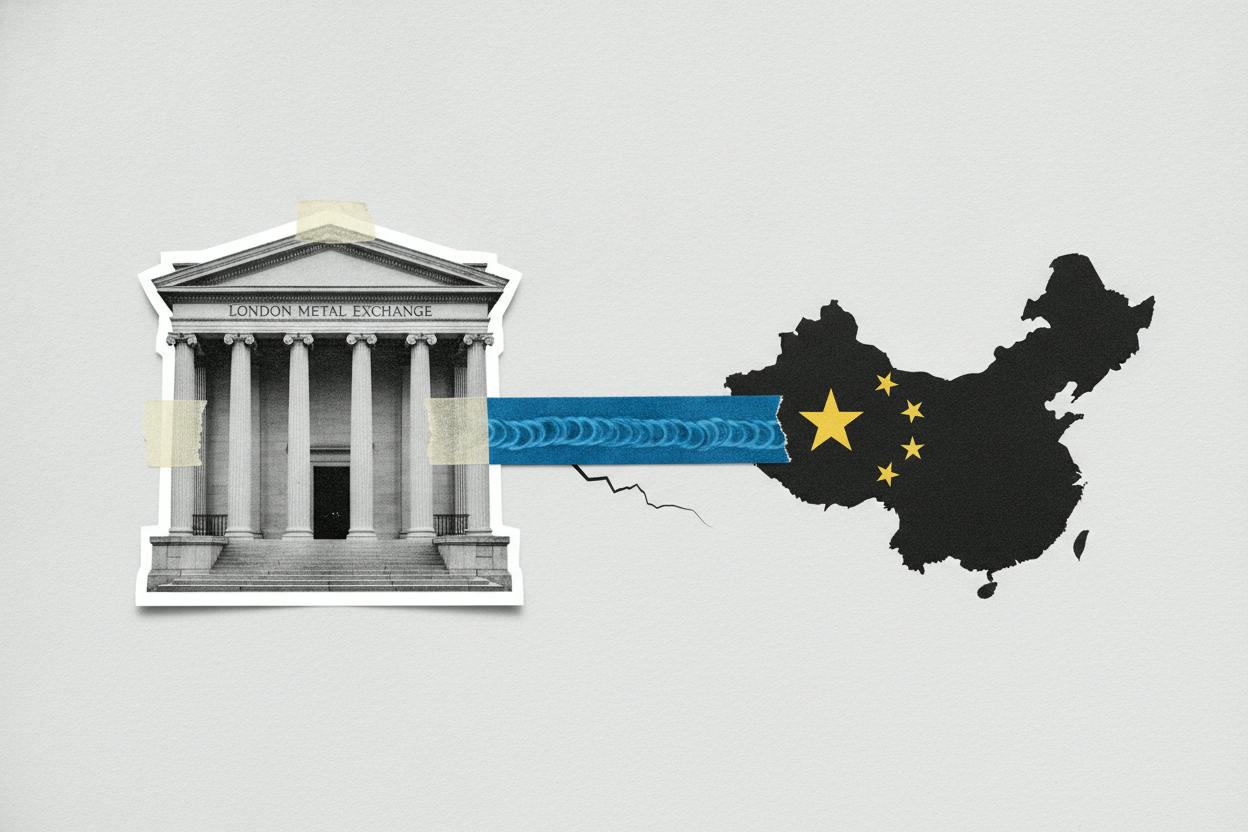
London Metal Exchange Week is underway, and the 149-year-old exchange has more spring in its step than many expected. After a turbulent few years, the LME posted record volumes in 2025, with average daily turnover up 16% year-on-year from January through September. And it's about to take a significant step closer to China by cross-listing a Steel Shanghai contract linked to the Shanghai Futures Exchange (ShFE) later this month.
A comeback from the nickel crisis
The LME's recent history has been dominated by the fallout from the March 2022 nickel crisis, when prices spiked violently and the exchange suspended trading and cancelled billions of dollars of trades. That episode shook confidence in the world's oldest and largest metals exchange. But according to Reuters columnist Andy Home, the crisis is fading. The exchange has since introduced reforms, including daily price limits and enhanced transparency, which appear to be restoring trust among market participants.
The recovery is also being helped by a broader backdrop of tariffs, geopolitical tension, and renewed interest in industrial metals. With supply chains under strain and governments prioritising strategic industries, metals like copper, aluminium, and steel have become more central to economic policy. That has translated into higher trading volumes and a busier exchange.
Steel Shanghai: a bridge to China
The next test for the LME is a hot-rolled coil (HRC) Steel Shanghai contract that settles against ShFE's HRC contract, a widely watched reference price for flat steel in Asia. This is the first time ShFE has allowed one of its metal prices to be used by another exchange, according to Home. It's a sign that relations between the two exchanges are thawing, and it could open the door to more collaboration in the future.
For the LME, the new contract is also a chance to breathe life into its underused ferrous lineup. The exchange lists seven steel contracts, but only three have traded this year, and combined volumes are down 29% year-on-year in the first nine months of 2026. The Steel Shanghai contract could attract real flow, especially from traders who want to hedge exposure to Asian steel prices.
What it means for investors
For everyday investors, the immediate impact is indirect but still relevant. The LME is a key global price-setting venue for industrial metals, and its health matters for anyone with exposure to mining stocks, steel producers, or commodity-focused funds. A more liquid and reliable LME can lead to better price discovery and lower hedging costs for companies, which can ultimately feed into their bottom lines.
More specifically, the cross-listing creates an arbitrage opportunity. When two exchanges list contracts that settle to the same underlying price, traders can buy on one and sell on the other to profit from any gap between the venues. That two-way arbitrage tends to narrow those gaps and make the prices line up more consistently. For steel producers, processors, and physical traders, the practical benefit is lower “basis risk” – the risk that a hedge moves differently from the real-world price you're exposed to – especially when buying or selling across Europe, the US, and Asia time zones.
If the contract attracts enough volume, it could also improve liquidity and price discovery for the LME's wider steel complex. That would be a positive for the exchange and for the companies that rely on it.
Broader market context
The LME's rebound comes at a time when global metals markets are being reshaped by geopolitical forces. Tariffs, export controls, and supply chain disruptions have made metals a strategic asset. The recent dip in Kazakhstan's copper output is a reminder that supply disruptions are never far away. Meanwhile, the push for electric vehicles and renewable energy is driving demand for metals like copper, lithium, and steel. Global EV sales slipped 2% in September, but Europe hit a record, and the long-term trend remains upward.
For investors, the key takeaway is that the LME is not just a relic of the past. It's adapting to a changing world, and its moves are worth watching. The Steel Shanghai contract is a small but symbolic step, and its success could have ripple effects across the metals complex.
What to watch next
Investors will be watching to see whether the Steel Shanghai contract attracts real trading volume in its first few months. If it does, it could signal a new era of cooperation between Western and Chinese exchanges. It could also encourage other Chinese exchanges to allow their prices to be used by foreign venues, which would be a major shift in the global metals landscape.
For now, the LME's recovery is a positive sign for the metals industry. But as always, the proof will be in the trading data. Keep an eye on the LME's monthly volume reports and the performance of the new contract.