Morgan Stanley reported third-quarter results that topped Wall Street's forecasts, but not all analysts are convinced the good times will last. Oppenheimer, an independent research firm, kept its underperform rating on the bank's stock, arguing that the earnings beat was largely powered by trading—a business that can be unpredictable.
The bank posted earnings per share of $3.03 on net revenue of $20.34 billion for the quarter ended September 30, both ahead of what analysts had expected. That headline beat might sound like a clear win, but Oppenheimer's caution highlights a deeper question: how sustainable is that growth?
Why trading is a double-edged sword
Trading revenue can swing sharply from quarter to quarter, depending on market volatility, client activity, and broader economic conditions. A strong quarter in trading doesn't guarantee the next one will be just as good. Oppenheimer's analysts noted that the latest beat was "largely driven by trading," which they see as a less reliable source of earnings than more steady businesses like wealth management or investment banking.
They also pointed to higher total expenses, including non-compensation costs tied to heavier activity and ongoing technology spending. Banks have been investing heavily in digital platforms and data infrastructure, and those costs can eat into profits if revenue growth slows.
The prime brokerage concern
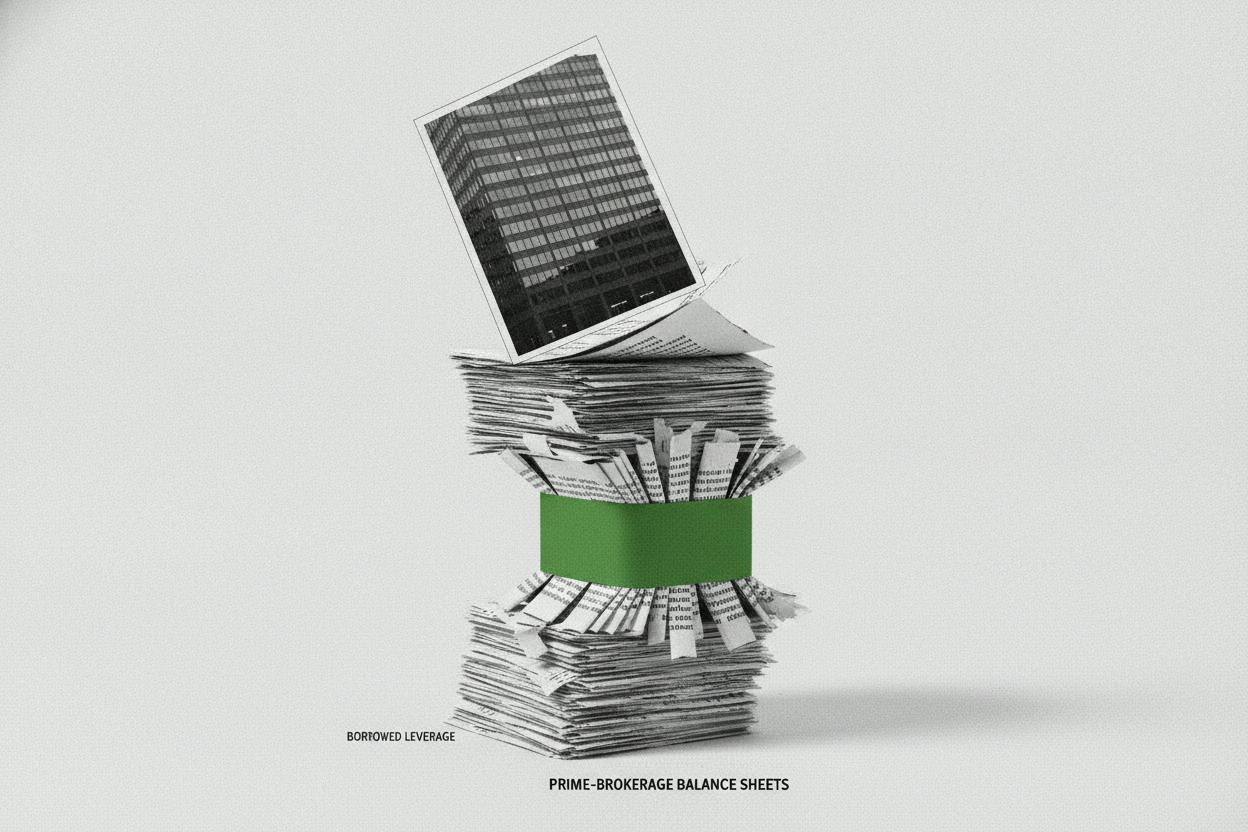
The bigger worry, according to Oppenheimer, is the rise in prime brokerage balances. Prime brokerage is a service banks offer to hedge funds and other large institutional clients, handling their trades, financing, and custody of assets. When these balances grow, it means the bank is taking on more exposure to the positions of its clients.
If those market positions turn sour—say, a big hedge fund bet goes wrong—the bank could face pressure on its revenue or even take losses. Oppenheimer warned that "bigger prime brokerage balances could pressure revenue if market positions turn." This is a reminder that banks that serve sophisticated investors are not immune to market shocks.
Morgan Stanley is one of the largest prime brokers in the world, alongside rivals like JPMorgan and Goldman Sachs. The business can be highly profitable in good times, but it also carries risk. In past market stress events, such as the 2021 collapse of Archegos Capital Management, prime brokers faced significant losses and legal fallout.
What it means for investors
For everyday investors, the key takeaway is that a single quarter's earnings beat doesn't always tell the full story. Morgan Stanley's results were strong, but the quality of those earnings matters. Trading-driven revenue can be volatile, and rising prime brokerage balances add a layer of risk that might not show up in the headline numbers.
Oppenheimer's underperform rating suggests the firm believes the stock may not deliver returns in line with the broader market. That's a signal for investors to consider whether the current valuation already reflects the good news, and to keep an eye on how the bank's risk profile evolves.
It's also worth noting that Morgan Stanley isn't alone in facing these dynamics. The broader banking sector has been navigating a mix of higher interest rates, shifting client activity, and increased regulatory scrutiny. JPMorgan's recent moves in the debt markets show that major banks are still active in financing big deals, but the environment remains complex.
Looking ahead
Investors will be watching several things in the coming months. First, whether Morgan Stanley can sustain its trading momentum or if it fades as markets calm. Second, how the bank manages its expenses, especially technology investments that are necessary but costly. Third, and most importantly, whether prime brokerage balances continue to climb and what that means for risk.
Oppenheimer's caution is a useful counterweight to the initial optimism around the earnings beat. While the bank's results were solid, the underlying risks are real. For those who own the stock, it's a reminder to look beyond the headline numbers and consider the sustainability of earnings. For those thinking about buying, it's a reason to do their own research and weigh the potential rewards against the risks.
As always, no single analyst rating should be taken as gospel. But when a respected firm like Oppenheimer flags concerns, it's worth paying attention. The market will ultimately decide, but understanding the nuances can help investors make more informed decisions.