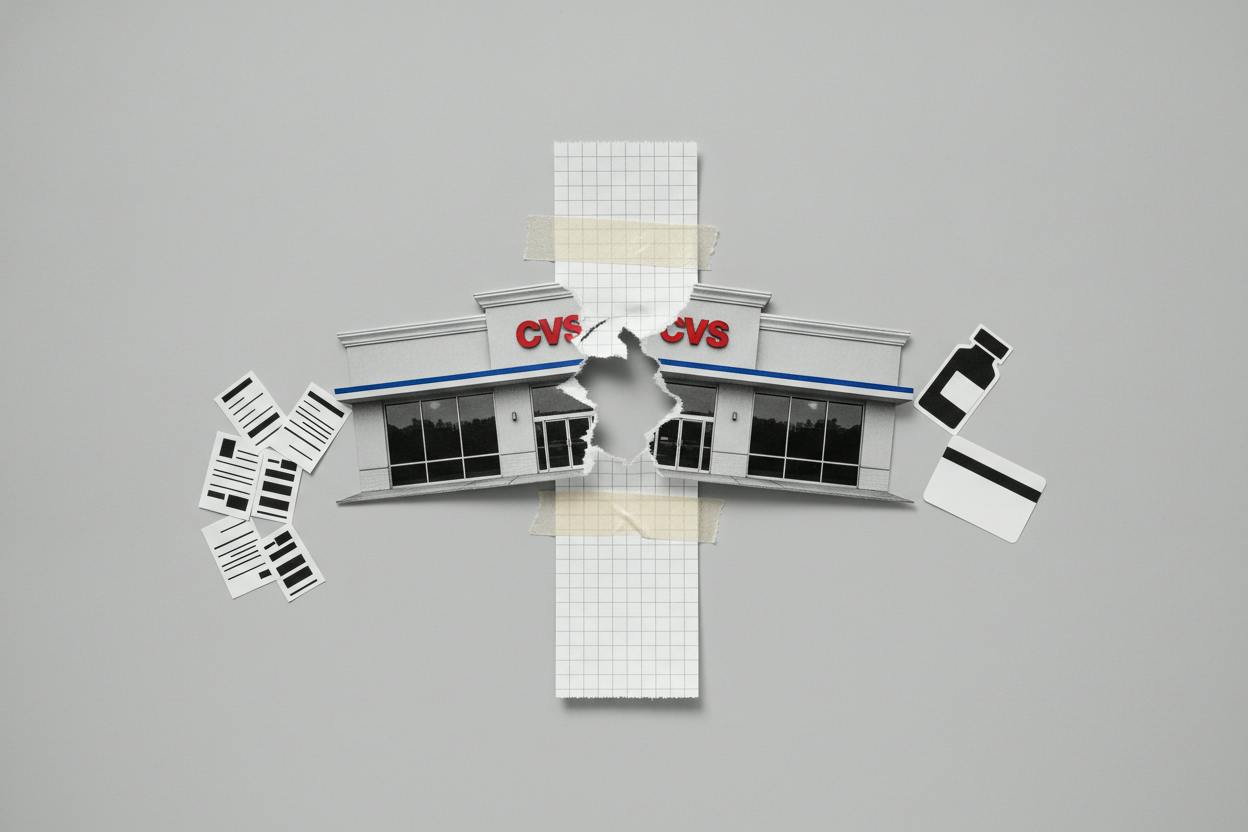
CVS Health is exploring a breakup that would separate its roughly 9,000-store pharmacy chain from Aetna insurance and Caremark, its pharmacy-benefit manager, according to the Wall Street Journal and Reuters. The move, still in early testing stages, would mark a dramatic reversal of the company's long-held strategy of combining insurance, drug-price negotiating, and storefront pharmacies under one roof.
For everyday investors, the news raises big questions about the future of one of America's largest healthcare companies. CVS has spent years building an integrated model that aimed to control costs and improve care by connecting how drugs are priced, how patients get them, and how insurance pays for them. A split would unwind much of that vision.
What's behind the potential split?
CVS's current structure has three main parts: its retail pharmacies, Aetna's health insurance plans, and Caremark, which manages prescription drug benefits for employers and insurers. The idea was that these pieces would feed each other—pharmacies would fill prescriptions, Caremark would negotiate drug prices, and Aetna would provide the insurance coverage.
That strategy took shape through major deals, most notably the $78 billion purchase of Aetna in 2018. At the time, CVS argued that combining these businesses would let it lower costs and offer more coordinated care. But the reality has been more complicated. The company has faced pressure from falling pharmacy margins, rising competition, and regulatory scrutiny over how pharmacy-benefit managers (PBMs) negotiate drug prices.
PBMs like Caremark sit between drugmakers, insurers, and pharmacies, and they've come under fire for their role in high drug prices. Lawmakers and regulators have questioned whether PBMs inflate costs or squeeze independent pharmacies. That scrutiny has weighed on CVS's stock and made the PBM business a potential liability.
By separating the retail pharmacies from Aetna and Caremark, CVS could make each part easier to manage and potentially more attractive to investors. A standalone pharmacy chain might be valued differently than a company tangled up in insurance and PBM politics. Similarly, Aetna and Caremark could operate without the drag of thousands of physical stores.
What does this mean for investors?
For shareholders, a breakup could unlock value if the market believes the parts are worth more than the whole. Conglomerates often trade at a discount because investors struggle to value diverse businesses under one roof. Splitting them up can force a clearer picture of each unit's financial health.
But breakups also come with costs and risks. Separating operations takes time and money, and it can disrupt customers and employees. There's also no guarantee that a split will lead to higher returns. Companies in this position often see short-term stock pops on news of a potential breakup, but the long-term outcome depends on how well each standalone business performs.
Investors should also consider the broader context. CVS has been dealing with falling pharmacy reimbursement rates, competition from Amazon and other online retailers, and a tough environment for health insurers. A breakup wouldn't solve those problems by itself—it would just change how they're managed.
The reports say the company is "testing" a breakup, which suggests no final decision has been made. That means investors shouldn't expect immediate changes. Instead, they should watch for any official announcement, details on how the businesses would be divided, and what the company says about the rationale.
What to watch next
If CVS moves forward, the key questions will be about structure: Would the pharmacy chain be spun off to existing shareholders, or sold? Would Aetna and Caremark stay together or also be separated? And what would happen to the company's debt and cash flow?
Other large companies have gone through similar splits in recent years, often with mixed results. Some have succeeded in unlocking value, while others have found that the parts were weaker than expected on their own. The healthcare sector is particularly complex because of regulation and the interconnected nature of the businesses.
For now, the news is a signal that CVS's leadership is open to big changes. That could be a positive for investors who have been frustrated by the stock's performance, but it's also a reminder that strategic overhauls don't always deliver immediate rewards.
As always, it's worth keeping an eye on how the company communicates its plans. Any breakup would need approval from the board and likely regulators, so there's a long road ahead. Investors should focus on the fundamentals—how each business performs on its own—rather than getting caught up in speculation.