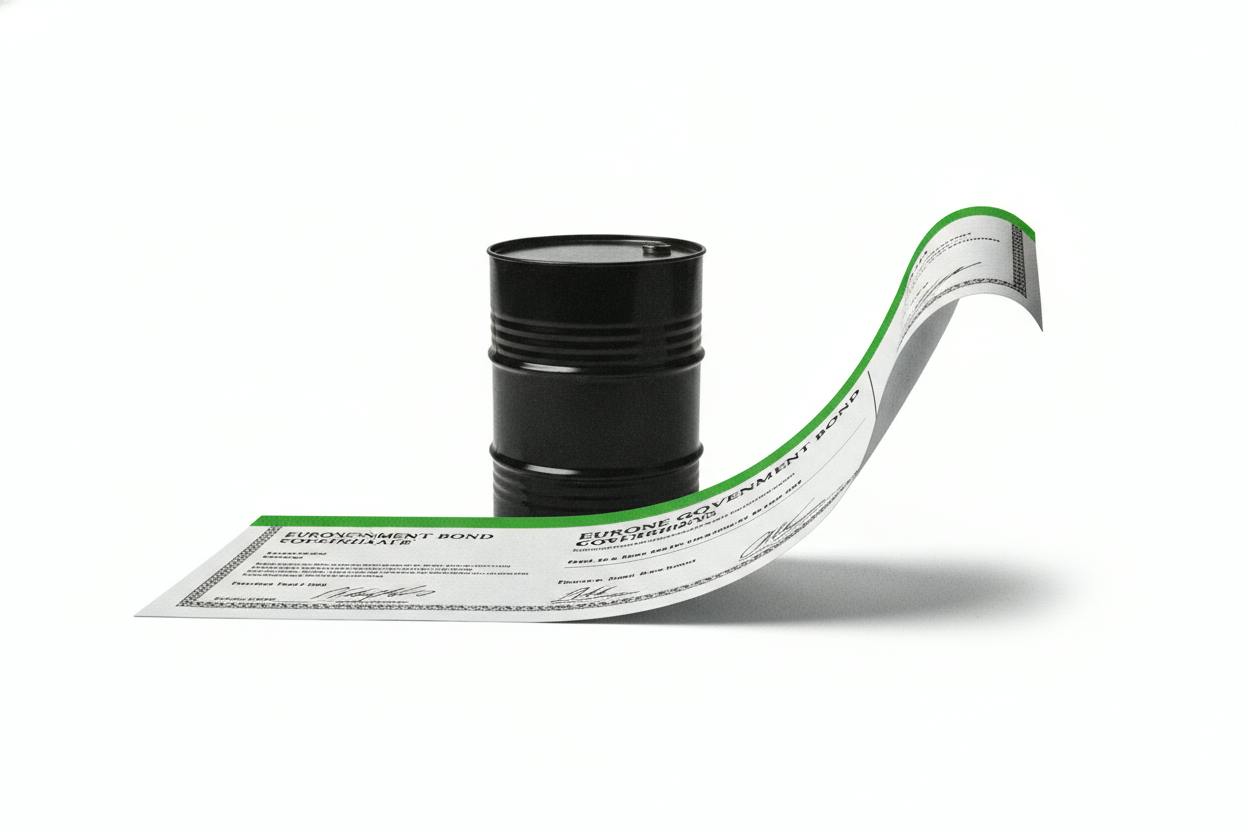
A fresh wave of selling hit eurozone government bonds on Tuesday, pushing long-term borrowing costs to levels not seen in 17 years. Germany's 10-year yield climbed to 3.572%, while France's 30-year yield approached 5.2% and Germany's 30-year topped 3.9%. The move marks a sharp leg higher in a weeks-long creep that has now erased the post-crisis era of ultra-low rates.
The trigger, as so often this year, was energy. Oil prices jumped as tensions in the Middle East escalated, with Brent crude trading above $107 a barrel. Higher energy costs feed directly into inflation, and that forces bond investors to demand higher yields to compensate for the erosion of their fixed returns.
Why yields are rising
Bond yields move inversely to prices. When investors sell bonds, prices fall and yields rise. The current selloff is concentrated at the long end of the curve—the 10-year and 30-year maturities—where investors are most worried about inflation staying elevated for years to come.
Part of the pressure is imported from the United States. The 10-year Treasury yield is now approaching 5%, a level that has historically acted as a psychological barrier. When US yields rise, they pull global yields up with them, because investors can earn a similar return in the world's safest market without taking on currency or credit risk.
For Europe, the move is particularly significant. Germany's 10-year yield at 3.572% is the highest since before the eurozone debt crisis of the early 2010s. That crisis was defined by fears that heavily indebted countries might default, but today's move is different: it is driven by inflation and the European Central Bank's determination to keep rates restrictive.
What this means for your money
For everyday investors, rising bond yields have a ripple effect. Government bonds are the benchmark for borrowing costs across the economy. When they rise, so do mortgage rates, corporate borrowing costs, and even the interest you earn on savings accounts.
Higher yields also put pressure on stock valuations. When bonds offer a decent return with low risk, investors demand a higher return from equities to justify the extra risk. That is one reason why European stocks have been slipping as yields climb.
For those holding bond funds, the immediate impact is negative: prices fall as yields rise. But for investors with cash on the sidelines, higher yields mean better returns on short-term savings and money market funds. The trade-off is that locking in long-term bonds now could prove costly if yields keep climbing.
The oil factor
The jump in oil prices is the key variable. The Middle East conflict has raised fears of supply disruptions, and oil holding above $107 is a level that historically has coincided with economic stress. Energy is a major input for almost everything, so sustained high prices feed into broader inflation measures.
Germany's wholesale prices already jumped 6.8% year-on-year, a sign that energy costs are working their way through the economy. If oil stays high, central banks may have to keep interest rates higher for longer, which would keep upward pressure on yields.
What to watch next
Investors will be watching the US Federal Reserve's next policy decision, with the dollar near a two-week high as markets price in a more hawkish stance. The ECB is also in focus, as it balances the need to fight inflation against the risk of tipping the eurozone into recession.
For now, the direction of travel is clear: yields are rising, and that is tightening financial conditions globally. The question is how much further they can go before they start to bite. Historically, when 10-year yields approach 5% in the US, it has often marked a turning point—either for inflation, for growth, or for both.
For investors, the key takeaway is that the era of cheap money is firmly over. Bonds are no longer a safe haven that always rises in value; they are now a source of volatility. Diversification and a clear understanding of your own time horizon have never been more important.