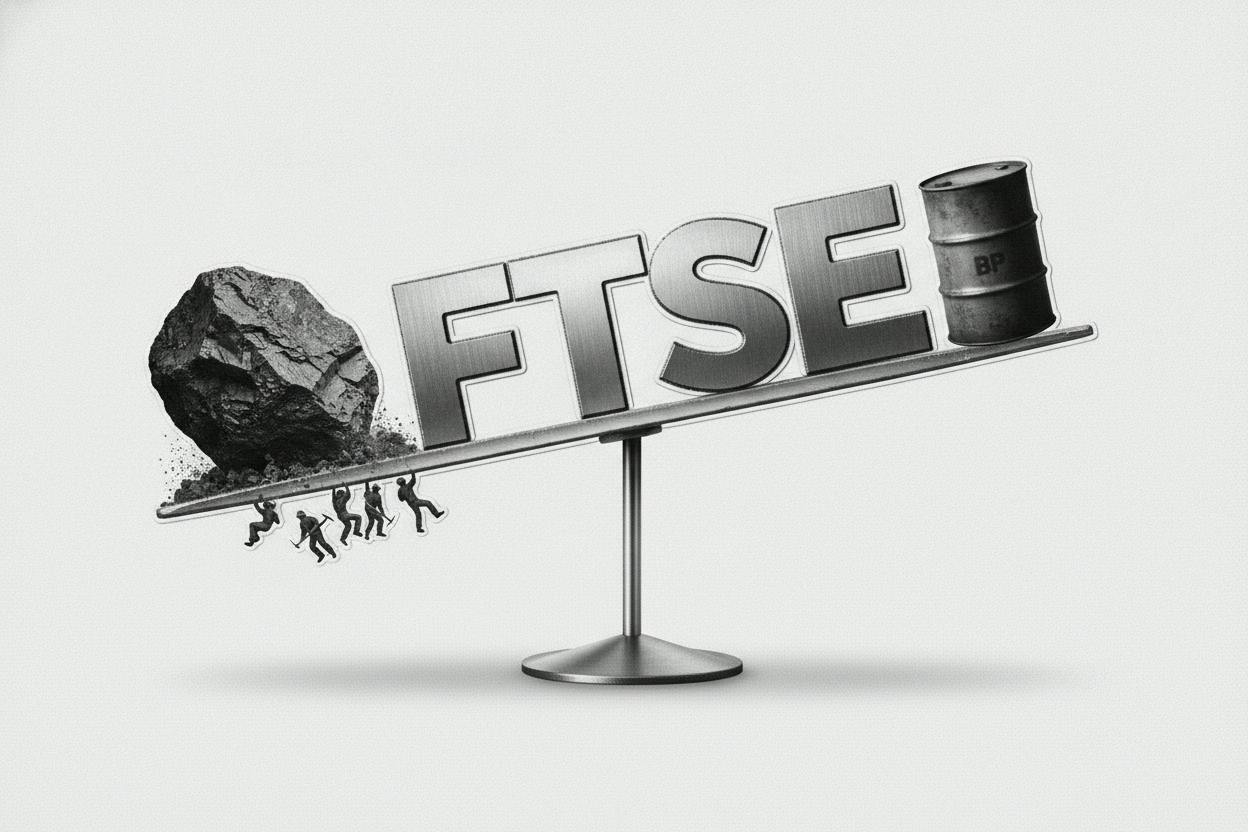
London's blue-chip index finished Tuesday almost exactly where it started, as weakness in mining shares offset a strong session for BP. The FTSE 100 slipped 0.06%, while the more domestically focused FTSE 250 added 0.05% — a split that underlined how much of the day's action came down to individual sectors rather than a single market-wide mood.
The muted close came as traders held back ahead of Wednesday's US inflation report, a data release that regularly sets the tone for global markets. With little fresh UK corporate or economic news to trade on, many investors chose to wait rather than take new positions.
Miners lead the decline
Metal producers did most of the damage. Precious-metal miners fell 1.4%, and industrial-metal specialists dropped 1.7%, according to the sector moves reported Tuesday. Copper miner Antofagasta was among the worst performers in the index, down 5.6%, as gold and silver prices eased and caution built before the US data.
Mining companies are especially sensitive to shifts in global growth expectations and the direction of the US dollar, because the metals they dig up are priced in dollars on world markets. When investors grow nervous about the economic outlook — or simply want to reduce risk before a major data release — these stocks are often the first to be sold. Copper in particular is watched as a barometer of industrial demand, so weakness in names like Antofagasta can reflect broader worries about construction and manufacturing activity. For more on how supply and demand dynamics have been shaping the copper market, see our coverage of copper's recent price swings.
Gold and silver miners, meanwhile, tend to move with the prices of the metals themselves. Both are seen as defensive assets, so a pullback in precious metals often signals that investors are feeling a little more willing to take on risk — or, as on Tuesday, that they are simply unwilling to make big bets before a key event.
BP provides the offset
Energy giant BP was the standout gainer, rising 3.7% after telling the market that its third-quarter refining margins had tripled compared with the same period a year earlier. Refining margins measure the gap between the cost of crude oil and the price at which refined products such as petrol, diesel and jet fuel are sold. When that spread widens, integrated oil companies with large refining operations can earn significantly more from every barrel they process.
BP's update is a reminder that the company is not just an oil producer — its downstream refining and trading businesses can be powerful profit drivers when conditions are favourable. The news helped lift sentiment toward the wider energy sector and provided a counterweight to the mining sell-off, which is why the FTSE 100's overall move was so small. Investors interested in how BP has been managing its balance sheet alongside these operational trends can read our earlier report on BP's debt reduction efforts.
Why US inflation matters to London
Wednesday's US inflation reading is the week's main event for global markets, and it matters just as much in London as on Wall Street. The data feeds directly into how the Federal Reserve thinks about interest rates. If inflation looks sticky, the Fed may keep rates higher for longer; if it cools more than expected, hopes for rate cuts could revive.
That matters for UK investors for a few reasons. First, US rates influence global borrowing costs, which affect everything from corporate profits to mortgage pricing. Second, the dollar often strengthens when US rates stay elevated, which can weigh on commodity prices and, by extension, on the FTSE's heavyweight mining sector. Third, shifts in US monetary policy tend to ripple through European and Asian markets, changing how investors allocate money across regions. Our coverage of recent Fed commentary on Treasury yields offers useful background on how policymakers are framing the debate.
What it means for investors
Days like Tuesday are a useful reminder that the FTSE 100 is not a single, unified bet on the UK economy. It is a collection of very different businesses — miners, oil majors, banks, consumer staples — whose fortunes can diverge sharply from one session to the next. A flat headline number can hide significant moves underneath.
For ordinary investors, the practical takeaways are:
- Sector exposure matters. If you hold a FTSE 100 tracker fund, you own a meaningful slice of mining and energy stocks, and their swings will shape your returns even when the index looks calm.
- Data days can be volatile. Markets often drift before major releases like US inflation, then move sharply once the numbers land. Short-term traders may see bigger swings on Wednesday.
- Company updates can move individual names. BP's refining news shows how a single operational disclosure can lift a stock regardless of the broader market direction.
- Currency is a hidden factor. A stronger dollar tends to pressure commodity prices and mining shares, so US inflation data can influence UK portfolios indirectly.
Looking ahead, investors will watch Wednesday's US inflation figures closely, along with any follow-up commentary from Fed officials. In London, attention will return to company-specific news and the pace of UK economic data, which has been mixed in recent months. For now, the market's message is simple: with a major data point looming, few were willing to make bold moves.