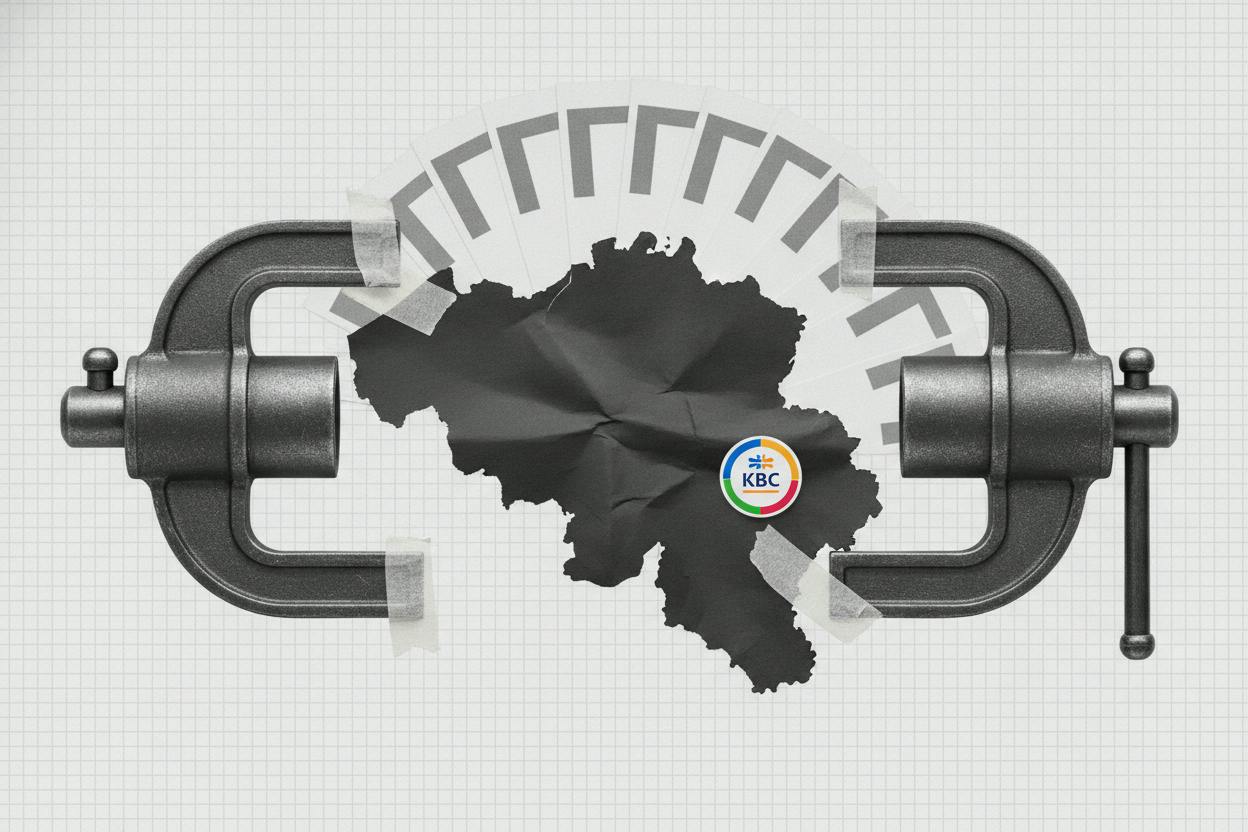
Belgian bank-insurer KBC reported third-quarter net profit of €1.14 billion on Thursday, meeting analyst expectations as strong insurance and trading income helped offset a squeeze on its core lending business. The result offers a snapshot of banking conditions across the eurozone and Central and Eastern Europe, where KBC operates significant franchises.
What drove the quarter
KBC's net-interest income — the difference between what it earns on loans and what it pays out on deposits — slipped to €1.77 billion, slightly below the €1.79 billion consensus. The decline was partly due to a hit from inflation-linked bonds, which reduced the income the bank generates from its bond portfolio.
That shortfall was more than made up for by strength in other areas. Insurance income and trading revenue both came in strong, helping the group post a net profit that matched what analysts had been expecting. For a bank that also runs large insurance operations, this diversification can act as a buffer when lending conditions turn less favourable.
Why KBC matters beyond Belgium
KBC is not just a domestic Belgian lender. It has major businesses in the Czech Republic, Hungary, Slovakia, and other countries in Central and Eastern Europe. That makes its results a useful barometer for how banks in the wider region are coping with interest-rate changes, inflation, and shifting consumer behaviour.
In recent years, central banks across Europe raised interest rates sharply to fight inflation, which initially boosted banks' net-interest income. But as rate hikes have paused and competition for deposits has intensified, that tailwind has faded. Banks are now paying more to hold onto customer deposits, while loan growth has slowed in some markets. KBC's experience this quarter reflects that broader trend.
The bank also flagged bond spreads as a growing risk. Bond spreads — the extra yield investors demand to hold riskier bonds compared with safer government debt — have been widening in some markets. For a bank that holds a large portfolio of bonds, wider spreads can mean lower valuations and reduced income from those holdings. It's a reminder that banks are not just exposed to interest rates but also to the health of the credit markets they operate in.
What it means for investors
For everyday investors, KBC's results show that a bank can still meet profit expectations even when its core lending business is under pressure. The key takeaway is the importance of diversification: KBC's insurance and trading arms helped offset the weakness in net-interest income, allowing the group to hit its targets.
However, the flag on bond spreads is worth watching. If credit conditions deteriorate further, banks with large bond portfolios could face additional headwinds. Investors should also keep an eye on how long the squeeze on lending margins lasts. If deposit costs continue to rise while loan growth stays sluggish, net-interest income could keep declining in coming quarters.
For those holding bank stocks or considering them, KBC's report is a reminder that the era of easy gains from higher interest rates may be over. Banks are now navigating a more complex environment where the quality of their other businesses — insurance, trading, and fee income — matters more than it did a year ago.
Broader market context
KBC's update comes at a time when investors are closely watching how banks across Europe and beyond are managing the shift in interest-rate expectations. In other markets, similar themes are playing out. For example, CBA's profit held steady but home loan arrears climbed, highlighting how lenders are dealing with rising borrower stress. Meanwhile, rising rates could ground stocks despite strong earnings, a concern that applies to banks as well.
In the US, Fossil stock jumped 25% on surprise profit and raised outlook, showing that companies can still beat expectations even in a tough environment. And in Brazil, Banco do Brasil halved its 2026 profit forecast as farm loan defaults climbed, a stark reminder that credit risk can emerge quickly in different sectors.
Looking ahead
Investors will now be watching KBC's next moves on capital returns, loan growth, and how it manages its bond portfolio in the face of wider spreads. The bank's ability to hit profit estimates despite the headwinds suggests its diversified model is holding up, but the risks it flagged are not going away.
For the broader banking sector, KBC's quarter reinforces that the post-rate-hike boom is fading. Banks that can generate income from non-lending activities — or that have strong cost control — are likely to fare better than those that rely heavily on net-interest income. As always, past performance is no guarantee of future results, and investors should consider their own financial situation before making any decisions.