India's rupee forward market is showing signs of strain after the Reserve Bank of India (RBI) tightened currency-market rules, pushing forward premiums to multi-year highs and making it more expensive for companies and investors to hedge their dollar exposure.
Forward contracts allow businesses and investors to lock in an exchange rate for a future date, so any disruption in this market can quickly ripple into funding costs and risk management. This week, traders told Reuters that liquidity dried up following the RBI's moves, and the cost of hedging dollars into rupees jumped. The one-year "implied hedging cost" rose to about 4.6%, the highest level since January 2022.
What are rupee forwards and why do they matter?
A forward contract is a financial agreement to exchange currencies at a predetermined rate on a future date. For example, an Indian company that expects to receive dollars in six months can use a forward to lock in today's rate, protecting itself from adverse currency moves. Similarly, foreign investors holding Indian assets often use forwards to hedge their rupee exposure.
The price of a forward is derived from the interest rate differential between the two currencies, plus supply and demand. When liquidity is thin, pricing becomes less efficient, and the gap between what buyers and sellers are willing to trade can widen. This is exactly what has happened in the rupee forward market, according to traders.
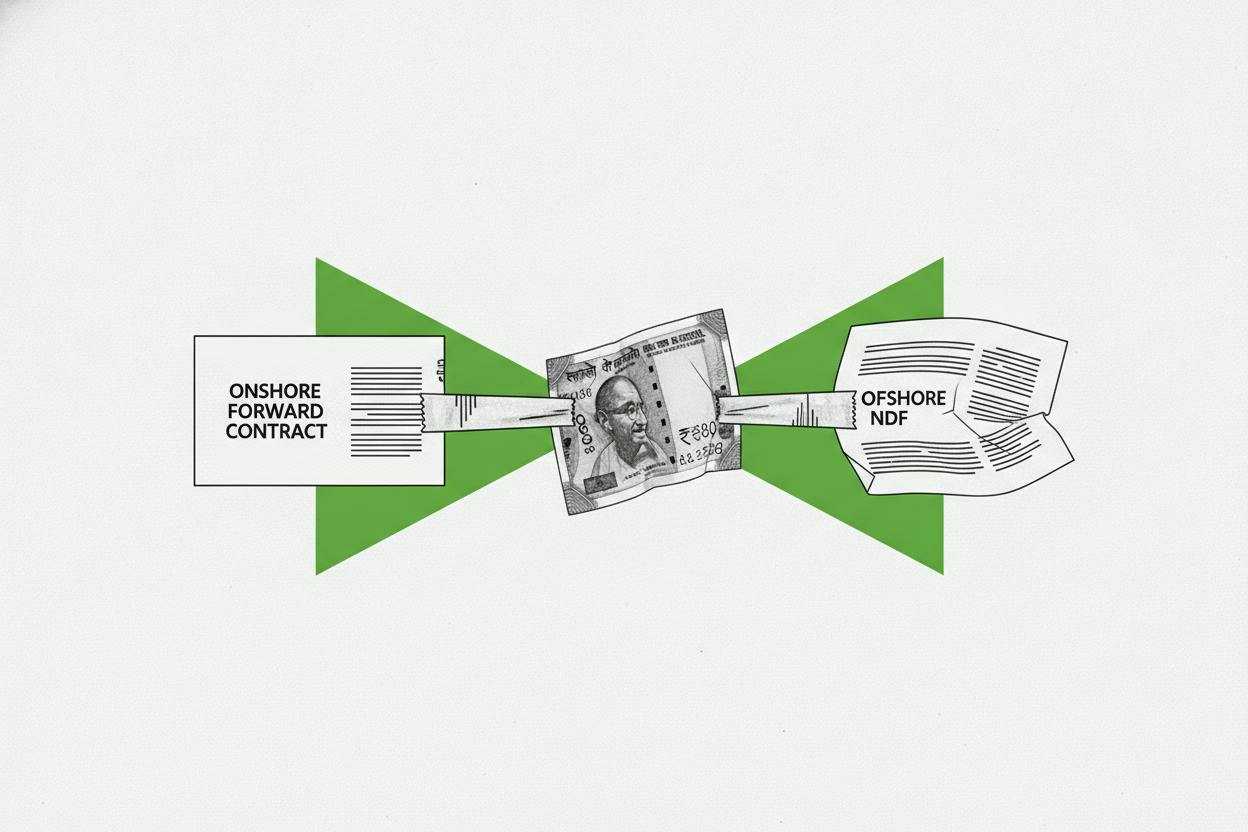
The RBI's recent tightening measures—aimed at curbing speculation and managing the rupee's value—have reduced the availability of rupee liquidity in the offshore market. As a result, the spread between onshore deliverable forwards and offshore non-deliverable forwards (NDFs) has widened, making it harder for banks and hedgers to align their pricing.
Why the RBI's actions matter
The RBI has been actively defending the rupee, which has come under pressure from global factors such as hot US inflation and a strong dollar. The central bank's quiet intervention at the 95 level has shifted pressure to the forward markets, as noted in our earlier coverage.
By tightening rules, the RBI aims to reduce speculative positions and smooth volatility. However, these measures can also reduce market depth, making it more expensive for genuine hedgers—like importers and exporters—to protect themselves. This is a classic trade-off: tighter regulation can bring stability, but it can also raise costs for participants.
The jump in implied hedging costs reflects this tension. For a company that needs to hedge a large dollar receivable, a 4.6% cost is significant. It means that locking in a future exchange rate now costs more than it has in years, which could eat into profit margins or force firms to reconsider their hedging strategies.
What it means for investors
For everyday investors, the immediate impact is indirect but real. If you hold Indian stocks or bonds, a weaker or more volatile rupee can affect your returns when converted back to your home currency. The RBI's actions are designed to prevent sharp depreciation, but the side effect is higher hedging costs, which can weigh on corporate earnings, especially for companies with significant foreign currency exposure.
Foreign investors have already been selling Indian equities at a record pace, partly due to US inflation concerns. The current dislocation in the forward market could add to the uncertainty, making it more expensive for foreign investors to hedge their rupee positions. This, in turn, could influence capital flows into Indian markets.
On the positive side, the RBI's intervention has helped keep the rupee from falling too sharply, which supports the value of Indian assets in dollar terms. The central bank has signaled no tolerance for weakness, which may reassure investors looking for stability.
However, the widening gap between onshore and offshore pricing is a sign that the market is not functioning smoothly. This could lead to arbitrage opportunities for sophisticated players, but for most investors, it simply means higher costs and more uncertainty.
Looking ahead
The key question is how long the RBI will maintain its current stance. If the central bank eases its tightening, liquidity could return and forward premiums could normalize. But if global pressures persist—such as hot US inflation and a strong dollar—the RBI may keep its foot on the brake, prolonging the dislocation.
Investors should watch for any signs of policy adjustment, as well as upcoming economic data such as India's trade gap and Q2 earnings, which are due in mid-October. These could provide clues about the rupee's trajectory and the RBI's next moves.
In the meantime, the message is clear: the rupee forward market is under stress, and that stress has a cost. For companies and investors alike, understanding these dynamics is essential to navigating the current environment.