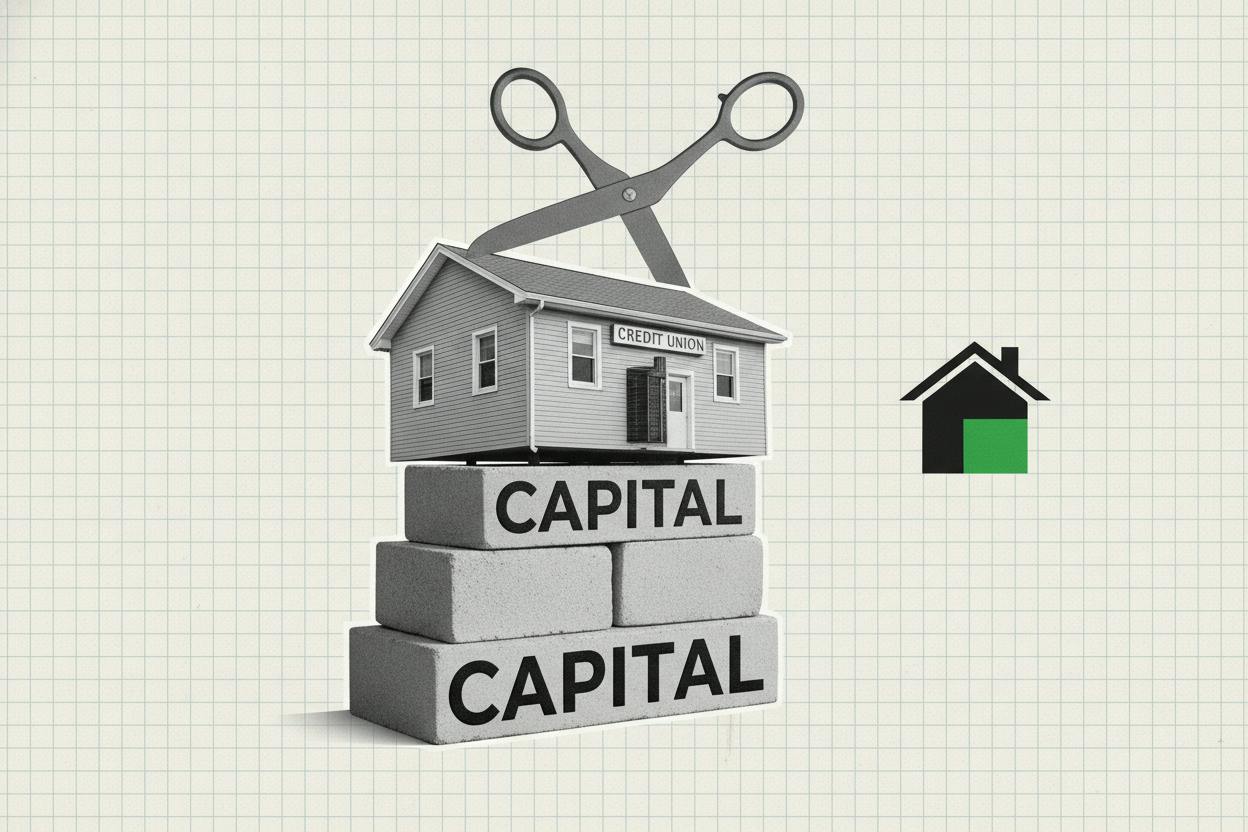
Canada's banking regulator is proposing to lighten the capital load on smaller banks and credit unions, a move aimed at shaking up a sector long dominated by the country's biggest lenders. The Office of the Superintendent of Financial Institutions (OSFI) wants to lower the amount of capital these institutions must hold against certain low-risk mortgages, with final changes expected to land in late 2027 or early 2028.
Why OSFI is acting
The rationale is straightforward: Canada's banking system is heavily concentrated. The Big Six banks—RBC, TD, Scotiabank, BMO, CIBC, and National Bank—control the vast majority of assets, and years of consolidation have thinned the ranks of mid-sized challengers. OSFI believes this concentration is partly a result of a "capital gap." Smaller lenders often end up having to set aside more of their own money behind loans that are similar to those made by the big banks. That higher capital requirement limits how aggressively they can grow, because every dollar parked as a buffer is a dollar not available for lending or expansion.
By lowering capital requirements for smaller institutions, OSFI hopes to close that gap and make it easier for them to compete. The idea is that with less capital tied up, these lenders can offer more attractive mortgage rates or loosen their lending criteria slightly, drawing customers away from the Big Six and fostering a more competitive market.
What this means for the banking landscape
For everyday Canadians, the potential upside is more choice and potentially better pricing on mortgages and other loans. If smaller banks and credit unions can grow their market share, the Big Six may have to respond with more competitive offers to retain customers. That could translate into lower borrowing costs for consumers, though the effect is unlikely to be immediate—the proposed changes won't take effect until late 2027 or early 2028 at the earliest.
For investors, the proposal is a signal that regulators are paying attention to the competitive dynamics of the banking sector. It's a reminder that the regulatory environment can shift, and that smaller financial institutions could become more formidable competitors over time. However, the timeline is long, and the final rules could still change before they are implemented.
What to watch next
OSFI will now consult with industry stakeholders before finalizing the rules. The key details to watch include the exact size thresholds for which institutions qualify for the lower capital requirements, and how the regulator defines "low-risk mortgages." The outcome will determine how much of a boost smaller lenders actually get.
This isn't the only regulatory or market development on the horizon for Canadian finance. The broader backdrop includes a return of mega-deals in energy and banking, and record foreign investment in Canadian short-term debt, both of which signal shifting investor sentiment. Additionally, the loonie's recent weakness and trade tensions with the US could influence the broader economic environment in which these banks operate.
What it means for investors
For investors in Canadian bank stocks, the proposal is a modest headwind for the Big Six, as it could eventually erode their market dominance. But the impact is likely to be gradual and manageable. For investors in smaller banks and credit unions, the changes could be a tailwind, potentially improving their growth prospects and profitability.
It's also worth noting that capital requirements are just one factor in a bank's ability to compete. Access to funding, brand recognition, and distribution networks all play a role. The Big Six are unlikely to lose their grip anytime soon, but a more level playing field could benefit consumers and smaller players alike.
As with any regulatory proposal, there's no guarantee the final rules will match the initial proposal. But the direction is clear: Canada's banking watchdog wants a more competitive sector, and it's willing to adjust the rules to get there.